Anthem PPO vs. HMO vs. HIP: How Your Plan Type Changes Mental Health Coverage
August 3, 2026
Does Health Insurance Even Cover Mental Health Treatment? What the Law Requires
August 7, 2026
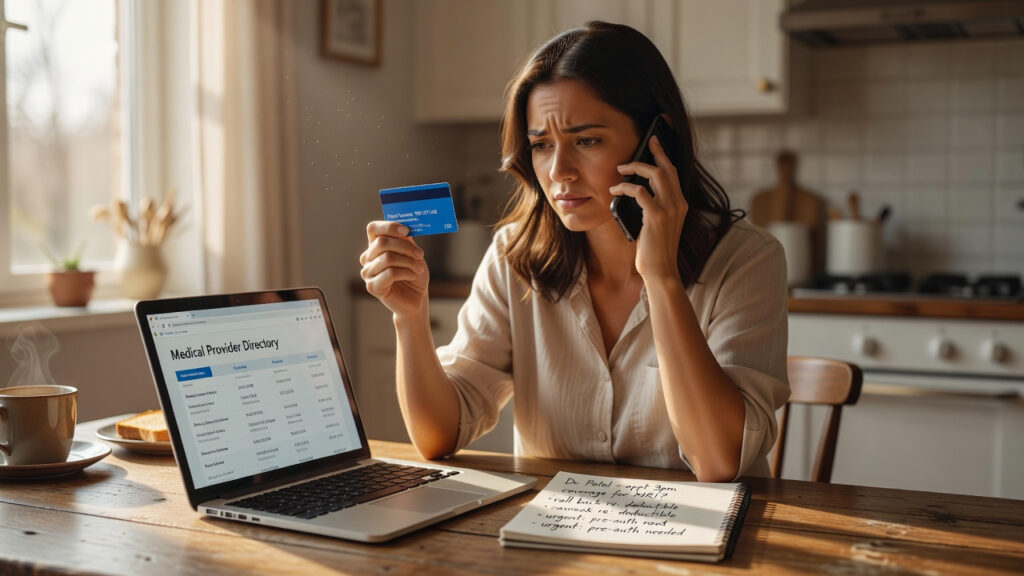
Anthem tells you mental health is covered. Cool. That means almost nothing until you know which service, which provider, and which version of your specific plan you’re actually holding. We watched people assume “in-network” and “accepts Anthem” mean the same thing, then get hit with a bill that reads like a typo. It isn’t a typo. It’s the gap between having a behavioral health benefit and knowing whether your appointment, with your therapist, on your plan, actually falls inside it.
The questions to ask when verifying insurance benefits help in verifying your Anthem mental health benefits before you schedule anything; it is the only way to close that gap, and it takes maybe fifteen minutes on the phone or through Availity if your provider’s office uses it.
Key takeaways:
- Coverage for “mental health” broadly does not guarantee coverage for the exact service, code, or provider you’re planning to use.
- “Accepts Anthem” and “in-network for your plan” are two different claims, and mixing them up is the single most common cause of surprise bills.
- Document everything: date, representative name, reference number, plan name, and what was actually said about your deductible, copay, and authorization rules.
Does having Anthem insurance mean therapy is automatically covered?
Question: Does having Anthem insurance mean therapy is automatically covered?
Answer: Not automatically, no. Anthem Blue Cross and Anthem Blue Cross Blue Shield plans vary by employer group, state, and network tier, so behavioral health benefits differ from one plan to the next. You have to verify the specific service and provider, not just the general category.
Start With These 5 Questions About Your Anthem Mental Health Coverage
Before you get lost in deductible math, anchor the call with five questions that cut straight to the point. Ask whether your specific Anthem plan includes coverage for the mental health service you need, whether the provider you want is in network for that exact plan, what you’ll actually pay for the visit, whether you need a referral or prior authorization, and whether there are visit limits or exclusions worth knowing about now rather than after the fact.
A generic “yes, mental health is covered” from a phone rep isn’t really an answer. It’s a placeholder. Push past it. Ask them to reference the specific CPT code your provider expects to bill, because coverage decisions live at the code level, not the category level.
Which Mental Health Services Are Covered
This is where people get sloppy. Asking “is therapy covered” is too broad, because Anthem treats individual outpatient counseling, couples therapy, psychiatric evaluations, medication management, psychological testing, group therapy, intensive outpatient programs, partial hospitalization, inpatient treatment, and substance use disorder services as distinct benefit categories, sometimes with separate rules entirely.
| Service | Question to ask | Why it matters |
|---|---|---|
| Individual outpatient therapy | Is this covered under my behavioral health benefit? | Most common service, but exclusions still exist on some plans |
| Psychiatric evaluation/medication management | Is this billed and covered separately from therapy? | Often a different copay tier |
| Intensive outpatient/partial hospitalization | Does this require precertification? | Higher-cost care usually has stricter review |
| Substance use disorder treatment | Is this under the same benefit as mental health? | Some plans separate these, some don’t |
Covered doesn’t mean free, either. How to verify Anthem mental health benefits? It just means the claim has a pathway to payment, assuming everything else lines up.
In-Network vs. Out-of-Network: The Distinction That Actually Matters
Here’s the mistake I see constantly: someone calls a provider, the provider says “we take Anthem,” and the patient assumes that settles it. It doesn’t. A provider can accept Anthem as an insurance company, meaning they’ll bill the plan, without being contracted or in-network for that specific plan or network tier. Anthem’s national footprint includes multiple regional networks, and something like a Blue Shield Colorado plan may not overlap the same way a different state’s network does.
Ask the provider and the insurer separately whether the provider is in network for your exact plan, not just “Anthem” as a brand. If they’re out of network, ask what your out-of-network mental health benefits look like, what deductible applies, what percentage of the allowed amount the plan pays, and whether there’s a separate out-of-network out-of-pocket maximum. Also ask who submits the claim, because out-of-network providers sometimes leave that task to you.
Skip the question “do you accept Anthem.” Replace it with: “Are you in network for my specific Anthem plan, and can you confirm the plan or network name?” That one phrasing change avoids most of the confusion.
What You’ll Actually Pay
Deductible, copay, coinsurance, allowed amount, out-of-pocket maximum. These terms get thrown around like everyone already understands them, and frankly, most people don’t, not fully. Your deductible is what you pay before the plan starts sharing costs. Your copay is a flat fee per visit.
Coinsurance is a percentage split after the deductible is met. The allowed amount is what the insurer has negotiated as the “real” price of the service, regardless of what’s billed. The out-of-pocket maximum is the ceiling on what you’ll pay in a plan year, combining deductible, copay, and coinsurance together.
Ask whether you’ve met your deductible, whether it applies to outpatient mental health visits specifically, what your copay is for an in-network session, whether coinsurance applies and at what rate, and whether psychiatrist visits cost differently than therapist visits. Ask if telehealth pricing differs from in-person pricing too, because some plans still treat those separately even years after virtual care became routine.
A quoted copay of $30 doesn’t mean $30 is your ceiling. If the appointment includes psychological testing or a separate billed component, you could owe more than the number you were given over the phone.
Referrals, Prior Authorization, and the Fine Print
Not every service needs a referral or precertification, but some do, and getting this wrong is a fast way toward a denial. Ask whether your plan requires a referral from a primary care provider, whether prior authorization applies to the specific service, who’s responsible for filing that authorization (sometimes it’s the provider, sometimes it falls on you), and whether authorization needs to happen before the first visit or can follow a certain number of sessions. Intensive outpatient, partial hospitalization, and inpatient levels of care almost always carry stricter review than a standard outpatient visit.
Benefits verification and authorization aren’t interchangeable, either. You can verify that a service is generally covered and still get denied later because authorization wasn’t secured in time. According to CMS guidance on provider billing responsibilities, verifying prior authorization and coordinating with the payer ahead of service delivery is one of the clearest ways to prevent claim denial before it happens.
Telehealth and Virtual Mental Health Care
If you’re leaning toward video sessions instead of an office visit, ask whether virtual mental health care is covered under your plan, whether telehealth visits carry the same deductible, copay, and coinsurance as in-person sessions, and whether the provider needs to be licensed in the state where you’re physically located during the appointment.
Some plans also restrict which platforms or provider networks qualify, and a few still require video rather than phone-only sessions to count as a covered telehealth visit. Don’t assume Anthem’s telehealth rules are uniform across every plan, because they genuinely aren’t.
When Weekly Therapy Isn’t Enough
Sometimes outpatient therapy isn’t sufficient, and the treatment team recommends something more intensive: psychiatric care, an intensive outpatient program, partial hospitalization, residential treatment where applicable, inpatient stabilization, or crisis services.
What to ask insurance about mental health coverage? Ask whether that level of care is covered, whether it needs prior authorization, whether specific facilities or providers are required, what cost-sharing applies, and what happens procedurally if your team later recommends stepping up to an even higher level.
Medical-necessity criteria and utilization review often kick in here, and Anthem’s process for reviewing these claims tends to be more involved than a routine outpatient visit.
What to Ask the Provider’s Office Directly
The insurer isn’t the only source of truth. Ask the provider whether they accept your specific Anthem plan, whether they’re in network, what insurance information they need before your first appointment, what CPT code they typically bill for sessions like yours, and how billing works if Anthem doesn’t pay the claim the way everyone expected. Providers can walk you through their own billing practices, but they can’t guarantee what the insurer ultimately decides. Only Anthem can confirm that.
Documenting What You Learn
Every call needs a paper trail. Note the date, the phone number or portal you used, the representative’s name or ID if they gave one, a reference number, the plan and network name, the service discussed, the provider or facility, network status, deductible standing, copay or coinsurance figures, authorization requirements, and any exclusions mentioned. This record becomes your evidence if a bill later doesn’t match what you were told during verification.
The Full Verification Checklist
- Confirm your exact Anthem plan and network name.
- Confirm the specific service and CPT code are covered, not just “mental health” broadly.
- Confirm provider or facility network status directly with both parties.
- Ask about deductible, copay, coinsurance, and out-of-pocket maximum.
- Ask about referral, prior authorization, and telehealth-specific rules.
- Record every detail from the call, then confirm billing specifics with the provider’s office before your appointment.
What Verification Can and Can’t Promise You
Verification tells you whether a service appears covered, what network status looks like, what cost-sharing is expected, and what authorization rules currently apply. It does not guarantee final claim payment, confirm medical necessity, lock in an exact dollar amount you’ll owe, or promise that every component of an appointment will be billed the same way.
The CMS Explanation of Benefits guide is a useful reference for understanding how the final itemized breakdown differs from a pre-service estimate, and it’s worth reading once so the terminology doesn’t blindside you later.
Next Steps
Once you’ve confirmed the plan, the specific service, expected cost-sharing, and any authorization requirements, and you’ve saved that information somewhere you’ll actually find it again, you’re in a decent position to schedule care with confidence.
Contact Anthem or First City Mental Health Center directly for anything plan-specific, since that’s the only authoritative source for your exact coverage details.
FAQs
1. Does Anthem insurance automatically cover mental health therapy?
No. Mental health coverage varies by Anthem plan, employer group, state, network, and specific service. You should verify your exact plan and the service you need before scheduling care.
2. How do I know if my therapist is in-network with Anthem?
Ask both the therapist’s office and Anthem whether the provider is in-network for your specific Anthem plan and network. Simply asking whether a provider “accepts Anthem” does not confirm in-network status.
3. What should I ask Anthem before scheduling mental health treatment?
Ask whether the specific service is covered, whether your provider is in-network, what your deductible, copay, or coinsurance will be, whether prior authorization or a referral is required, and whether any visit limits or exclusions apply.
4. Does Anthem cover telehealth mental health services?
Telehealth coverage depends on your specific Anthem plan. Ask whether virtual visits are covered and whether they have the same deductible, copay, and coinsurance as in-person appointments.
5. Does verifying my Anthem benefits guarantee that my claim will be paid?
No. Benefits verification can clarify apparent coverage, network status, expected cost-sharing, and authorization requirements, but it does not guarantee final claim payment or the exact amount you will owe.